
How the best betting exchanges in the UK really work — and what they charge the punter
 Available in US
A betting exchange is a marketplace where customers bet against each other, with the operator taking a slice of net winnings as commission rather than baking a margin into the odds. The result is a different kind of price than a bookmaker sells, and the page that follows puts a number on what that difference costs a British punter. Everything below is current as of 27 October 2026, with licence claims cross-checked against the Gambling Commission’s public register.
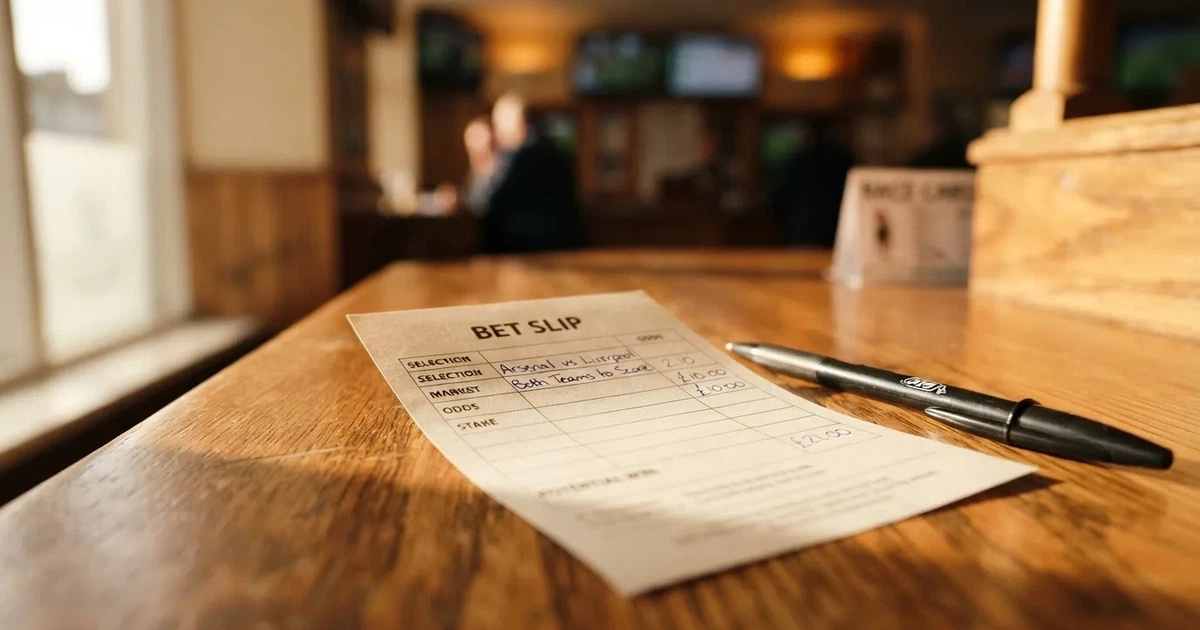
Smarkets’ terms show a standard 2% commission on net winnings per market — published on its own App Store page. Matchbook and Betfair publish their own commission rates too. Those two numbers carry more weight than the marketing language around them, because commission is where an exchange earns; the better the odds, the more a winning punter pays back into the platform. Side by side with the overround a bookmaker hides in a price, the picture looks nothing like the marketing.
For anyone comparing the licensed UK field, this is the long-form version: how a back bet and a lay bet settle, what real commission rates are, where the customer-protection duties sit on a site that takes a Gambling Commission licence, and what a punter gives up the moment they go off-piste to an offshore brand.
What an exchange costs the punter: the bonus and free-bet picture
The bonus culture at exchanges runs quieter than it does at bookmakers, and the reason is the structure. An exchange earns a percentage of net winnings, not a margin hidden in price, so a “100% bonus” on a deposit would only be repaid out of the operator’s commission on the bets the bonus attracts — a poor trade against the alternative of lowering the headline commission rate to win customers. What the field tends to publish instead is commission discounts and time-limited commission-free windows, with the bonus word used sparingly around the edges. Reading them carefully is the first cost-saving skill.
A typical exchange free-bet offer reads as a refund of a losing first bet in free-bet tokens, a matched-deposit free-bet envelope or, on a sportsbook attached to an exchange, the standard bookmaker welcome. None of these are gifts; each is a hook for a punter to wager the bonus amount several times over before a withdrawal clears, and the wagering multiple is the page that costs the most.
The promotion rules in force in Great Britain since 19 January 2026 cap wagering requirements on bonuses at 10x — at a £10 bonus that would be £100 of qualifying bets, not the higher figures older offers wrapped up in. Mixed-product promotions — an offer that requires gambling on two product types, for example “bet on football to get free spins” — are banned outright. Those two rules set the ceiling, not the floor: every legal British bonus fits underneath them, and an offer printed above the line is either misread by the punter or being sold from offshore where the cap does not bind.
The clearest way to compare offers across exchanges is not the headline percentage but the cost of clearing it. A £10 free bet at minimum decimal odds of 2.00, settled once on a single outcome, has a coupon value the punter can price in advance: a back bet at 2.00 returns £20 if it wins (£10 stake plus £10 profit), the £10 stake is not refunded on a free bet, so the punter’s at-stake money is zero and the ceiling of free-bet winnings is therefore the £10 profit. Below 2.00 the bonus pays less; above it the bonus value is unchanged by the higher price, but a higher price carries a higher chance of losing the stake altogether.
The national cap is one piece. The operator’s own terms are another. Most exchanges publish commission rates for the standard account and a separate, lower rate for a sharper account category — Smarkets and Betfair at the time of writing sit somewhere on this spectrum, and Matchbook’s published rate is in the same neighbourhood. The free-bet cost is the marketing number, the commission is the long-run cost: a punter who claims a £50 free bet at minimum odds 2.0 with a 5x wagering requirement is committing £250 of qualifying bets before withdrawal; on each of those bets the exchange will take commission on net winnings. The headline and the running cost are not the same number, and the second one is the bill.
The punter looking at any welcome offer has three checks before claiming. Is the wagering multiple inside the 10x cap? Is the offer a single product only — exchange or sportsbook, not both tied together? And what is the minimum decimal odds on a qualifying bet, because that figure decides how many of the qualifying bets can realistically win? A 1.5 odds floor is materially different from a 2.0 floor, even at the same multiple; a 1.5 floor lets a punter back the favourites with most of the rollover and shortens the path to a withdrawal, while a 2.0 floor forces a longer-shot.
The exchanges reviewed on this page do not lean on bonuses the way sportsbooks do. Where a sportsbook or exchange-sportsbook combination does, the marketing language is interchangeable with the wider market: “boosted odds”, “best odds guaranteed”, “acca insurance”, “free bet”, “100% bonus”. Each is a marketing word, and what each actually pays out is settled by the small print beside it. A boosted odds headline that looks like a 25% bigger price is only as good as the maximum stake the operator accepts and the markets on which the boost runs. An acca insurance that refunds one leg is only as good as the maximum refund the operator sets and the minimum number of legs the qualifying acca needs. A free bet token is only as good as the minimum odds allowed and the wagering requirement still hanging on the winnings. None of the words describes a cost in plain English; the cost is what the punter reads off the small type when they have already clicked through, and a comparison of offers is really a comparison of small type.
What the exchange model does best for the punter is make the long-run cost visible. Commission is published as a percentage; the odds are usually closer to the true price than a bookmaker’s; and the offer is harder to dress up as something it is not. None of that stops the marketing, but the maths is on the punter’s side: the offer costs what the small type says it costs, and nothing else.
Touchscreen and the betting app: what an exchange looks like on a phone
A betting exchange app is a thinner piece of software than a sportsbook app, by design. An exchange shows two columns — one for back, one for lay — with the backer wanting the selection to happen and the layer taking the bookmaker’s side by offering to win if it does not. The same selection in both columns at the same odds is what “matching” looks like, and unmatched bets sit in the order book until a counterparty appears. The whole purpose of the app is to render that order book fast enough that a punter can change prices during a football match or a horse race in play, and that pressure shapes every other decision: what notifications the app sends, how deep the market goes on a phone screen, and whether the app can be left open in the background while another window runs the live stream.
The leading UK-licensed exchanges publish iOS and Android apps with the same market depth as the desktop site in most events, and the differences that matter for a real punter are second-order. Apple App Store ratings are not a quality score, but a low rating correlated with a slow crash report on a Saturday afternoon tells the punter something. The app’s responsiveness to a market being suspended in play is a meaningful differentiator, and so is the depth of the order book on the undercard events that mainstream sportsbooks under-cover — handicap lines on a second-tier tennis event, for instance, or a cricket exchange where Smarkets and Betfair both ran markets before consolidation winnowed the field.
A punter who runs the betting app for cricket on a handset needs three things at once: the order book on the screen, the live scoreboard in another window or another tab, and the cash-out button ready at the moment the bowling changes ends. Where the exchange’s app exposes the order book with one tap and lets a back-or-lay order be amended without confirming it twice, the punter moves faster; where the app routes every amendment through a confirming dialog, the punter accepts that the displayed price may be gone by the time the order is confirmed. None of that is in any rating; it is in how the app behaves under load. Punters planning to use an exchange from a phone should test it at the busiest hour — Saturday football kick-off, the first race at Cheltenham — before staking real money on it.
The mobile browser version of an exchange is the other route in, and the trade-off is the same as for any web app: instant access without an install, but at the cost of features the native app would handle natively. Live-streaming in browser is heavier than in a native app, push notifications are browser-mediated and flaky on iOS, and the order-book refresh is usually slightly behind. Where the punter is on a desktop most of the day and a phone only for late-evening horse racing, the browser is fine; where the punter trades in-play on football, the native app is the better tool.
The Smarkets, Matchbook and Betfair apps each carry the trade on their respective store pages. Punters sometimes run more than one exchange app because each shows a slightly different price on the same selection — a typical situation at a Premier League match where the away-fan money sits on one platform and the home-fan money on another. The cost of running two apps is the data plan and the cognitive load; the benefit is the ability to take the better of the two displayed prices on the same selection. Without a comparable second app, the punter is stuck on whichever exchange first captured the order book, at whatever price sits there when the bet is clicked.
In-play and cash out: what the exchange does at full-time
A betting exchange and a sportsbook bookmaker handle in-play markets from different positions. The bookmaker owns the book and adjusts the margin as the event unfolds, sometimes widening the overround if the liability is uncomfortable. The exchange shows whatever the customers on both sides want to lay at the moment, and the displayed price is simply the cleared back and lay in the order book. Where the bookmaker’s cash-out button locks in a margin-adjusted figure, the exchange’s cash-out is a bet placed against the order book and the punter pays the spread between back and lay for the privilege of closing the position early.
Cash-out availability is not guaranteed at any operator. DAZN Bet’s published help article says so plainly: cash out availability is not guaranteed, and bets stand if it is unavailable — a customer-facing statement that makes the same point in different words. The same rule applies at the exchanges: if the market is suspended, the cash-out button is unavailable; if the order book is thin, the price offered is far from the last-traded; if no counterparty appears, the cash-out button is grey. The punter looking at a cash-out quote is looking at the gap between back and lay on the same selection at that moment, less the commission the exchange would take on the net winnings of the closing trade. That gap is real, and a wide gap makes a “lock in profit” button worth a lot less than its name suggests.
Live streaming at exchanges is part of the same package. Betfair’s sportsbook, for instance, offers free live streaming of UK and Irish horse racing and football within the app — a feature set that turns a phone into a betting terminal for racing. Matchbook’s app offers live streaming of horse racing and greyhounds on its exchange. The same constraint applies across the industry: streaming rights are limited to events the operator has paid for, and a punter at a less-stocked platform may find the stream missing for the very race they want to back.
In-play exchange punting is also where commission works hardest. A punter scalping a football match — backing at 2.02, laying at 1.98 if the price goes the right way, then closing the position before full-time — will pay commission on each leg, and the net figure is barely above zero. Spread betting scalping is a different model altogether, regulated by the FCA rather than the Commission and sitting on a separate licence: Spreadex operates both a spread-betting book under FCA rules and a fixed-odds book under Commission rules, and the spread side can produce losses larger than the deposit because it is leveraged. The punter comparing in-play across an exchange and a spread-betting operator is comparing two different products and should know which one they are in.
The cash-out decision is a question of value the punter makes on each bet, not on the platform. Where the cash-out price is within a small percentage of the back-or-lay quote at the same moment in the same market, the cost is the spread plus commission and a reasonable trade. Where the cash-out price is far from the traded price, the “lock in” button is locking in a loss the punter should let run. Markets go in and out of suspension around goals, wickets and major incidents, and the punter with an active position needs to know what to do during each suspension. Operators do not guarantee a cash-out quote through a suspension; the punter’s plan needs to account for that.
Trading on an exchange: predictions, systems and what they cost
A punter asking for a “system” or a “strategy” is asking how to convert an edge into a profit. The honest answer is that no system turns a negative expectation into a positive one, and exchange trading has its own particular shape: the variance of lay bets is higher than back bets at the same odds because a lay bet wins less often but pays more when it does, so a punter running a lay-the-favourite system needs a bank that can absorb a long run of favourites winning consecutively without exhausting the staking plan. The maths is brittle when the bankroll is small.
A betting exchange trading strategy that has stood the test of time is matched betting — using a free-bet offer at a sportsbook and laying the same selection at an exchange to lock in a small profit regardless of outcome. The technique is well documented, the long-run profit is bounded by the value of the free bets the punter can claim with the bookmakers prepared to take their action, and the long-run losses arrive when a bookmaker restricts the punter’s stake or closes the account. Matched bettors describe themselves as “mug bettors” in the messaging to a sportsbook because the bet is, by design, not the kind the operator wants.
Laying systems turn the bookmaker model on its head. A punter lays a selection when their model says the price on the lay side is too short; the punter wins when the selection loses, pays out when it wins, and the liability is the most they can lose in the worst case. The punter’s exposure is the liability, not the stake, and the bankroll needs to be sized to the liability rather than to the back stake. A £100 lay bet at 6.0 has a £500 liability (the backer would win £500 on a £100 stake at 6.0, all of which the layer would owe); the layer keeps the £100 stake if the selection loses. The punter’s accounting is from the liability, not the stake.
The strategies that look profitable in a backtest often do not survive a real exchange, because the exchange charges commission on net winnings. A scalping system with a 1% edge per trade at 100 trades per month is 100% gross per month, less 2% commission on each profitable trade; net, the system needs to clear the commission before any staking edge earns the punter a penny. The exchange charges the punter for the privilege of trading, and the system has to be designed around that charge rather than ignoring it.
Prediction content that points to specific selections is not a system — it is a tip, and tips are free because they are worth what the punter pays for them. A punter reading a tip should ask the tipster about their strike rate, their average winning odds, their sample size and whether the record is verified by an independent tracker; without that, the tip is anecdote dressed up in analysis. The exchange punter has an extra tool in the order book itself: where the lay side is heavy relative to the back side, the consensus backer view is one direction, and a model that disagrees with that consensus is one direction against the rest of the market. Following the lay side, betting alongside the consensus, is a different game from fading it — and a punter should know which one they are playing before staking.
Bankroll management is the most boring system and the most important. The punter with a £1,000 bank and a 2% commission per profitable trade cannot afford a system that loses more than £20 per trade in expectation, because commission plus losses will eat the bank before any edge has a chance to compound. The Kelly criterion gives a fraction of the bank to wager on each bet in proportion to the punter’s edge, and most professional exchange traders stake a fraction of full Kelly to dampen the variance — a 25% Kelly punter has a quarter of the theoretical optimal stake but a longer survival time. None of this is exotic; it is the price of being right for long enough that the variance has a chance to wash out.
The risk that no system mitigates is the suspension of markets around major events. A punter with an unmatched lay bet at 1.01 on a winning horse does not get a cash-out quote through the suspension; when the market resumes, the price is 1.01 because the horse won, the layer settles the bet and pays the backer. The punter’s “small profit if the horse loses” turns into a £5,000 liability if the horse wins, regardless of what system predicted the winner. Position sizing has to account for that.
Markets and odds: what an exchange lets a punter bet on
A betting exchange mirrors the mainstream sports markets a bookmaker offers and adds markets a bookmaker does not want to offer because the price is uneconomic. Lay markets across a full Premier League card. Asian handicap lines on minor tennis events. In-play markets with a 5-second refresh on the major horse-racing meetings. The exchanges that survived consolidation do not necessarily cover every sport — niche markets depend on whether enough customers sit on both sides of the order book to clear a bet — and the punter looking for a specific market should expect to check one or two platforms before staking.
Odds are stated in decimal or fractional form, and the exchange punter is comfortable with both. Fractional 5/1 is decimal 6.00, evens is 2.00, 9/10 — an odds-on favourite — is 1.90. The market quote of 1.01 to 1000 sits at the edges of the order book, with Betfair-style platforms allowing the wider range and more conservative exchanges limiting the lower bound to something tighter. Most betting exchanges cap prices at 1000 on one side and 1.01 on the other; the cap is a platform rule, not a market rule, and a punter pushing into the extremes should know where their chosen platform draws the line.
Accumulators — multiples of two or more selections whose odds multiply into a single price — work the same way at an exchange as at a sportsbook: a treble at 2.0, 3.0 and 4.0 carries a price of 24.0, and a winning £10 treble returns £240. The exchange’s edge over the sportsbook on a multiple is the lower commission on the winning end and the cleaner overround on each leg, but the punter has to remember that all four selections need to win — and the more legs, the more variance on top of the higher price. Each-way accumulators are typically handled at the sportsbook rather than the exchange, because each-way doubles the stake and complicates the order-book matching.
Bet builder products — same-game multiples assembled in the sportsbook — are also at the sportsbook end of most exchanges. Betfair’s sportsbook publishes Bet Builder as a product, and the exchange side runs the matched book on the assembled selection. The punter who wants a same-game acca and wants the exchange’s commission structure will need to assemble it at the sportsbook and then look for a lay quote at the exchange to lock in position — a workflow used by matched bettors and by exchange traders who want to take a position against a popular same-game multiple.
The punt is settled on the operator’s settled result, with non-runner, Rule 4 and dead-heat rules applying as on a sportsbook. Rule 4 deductions at an exchange are applied to the backer when a selection pulls out and the favourite shortens; the layer’s exposure narrows accordingly. A dead heat at horse racing reduces the backer’s stake proportionally; the layer’s liability is reduced in the same proportion. Non-runner rules are usually defined on the operator’s terms page.
Betting-exchange markets on horse racing and greyhound racing form the bulk of the volume in Great Britain, with football second and American sports third. Cricket markets have survived at fewer platforms, with the consolidation of the last decade shrinking the field to one or two serious operators. The punter should pick an exchange by the market they actually want, not by the headline commission rate; a lower commission on a thin market with poor liquidity is worse than a slightly higher commission on a deep, well-priced market.
The ranking: how the ten licensed UK exchanges compare
The ranked shortlist below mixes pure exchanges and exchange-sportsbook combinations because the British market licences both under the same set of categories — remote betting intermediary for exchanges and remote general betting standard (real events) for sportsbooks. Punters looking for matched betting or for the deeper order books should pick from the exchanges; punters looking for an exchange-sportsbook combination should pick from the dual-licence brands. Every brand on this list holds a Gambling Commission licence and is a GAMSTOP participant.
How to read the comparison
| Brand | Licence details | Operating terms on the key subject |
|---|---|---|
| Betfair | Commission account 39439 — PPB Counterparty Services Limited; categories on the register: remote general betting standard (real events) | The sportsbook arm runs in-play, Bet Builder, free live streaming of UK and Irish horse racing and football inside the app, and a 90 Minute Payout market; the exchange commission is set in the user’s account and disclosed on the platform terms |
| Smarkets | Commission account 39173 — Smarkets (Malta) Limited; category on the register: remote betting intermediary | Standard commission of 2% on eligible exchange bets, with a 0% commission window for new customers for 60 days subject to a £10 minimum first deposit |
| Matchbook | Commission account 39504 — Triplebet Limited; categories on the register: remote general betting standard (real events) and remote betting intermediary | A betting exchange where customers bet against other users; Bet Builder, multiples, in-play and live streaming of horse racing and greyhounds sit alongside the exchange order book |
| Kalooki Sportsbook | Commission account 57730 — Kalooki Sportsbook Limited; category on the register: remote general betting standard (real events) | Operator identity, GAMSTOP membership and a strict verification-before-deposit posture are stated on the operator’s homepage |
| BetTom | Commission account 64959 — Bet Tom Limited; category on the register: remote general betting standard (real events) | Sports welcome offer of 50% back as a free bet up to £50, with a matching 50% back up to £50 as free slot funds for casino play (full terms apply); described qualitatively, not as a working promo |
| DAZN Bet | Commission account 48756 — DZBT Limited; category on the register: remote general betting standard (real events) | Cash Out is offered but availability is not guaranteed and bets stand if it is unavailable — a plain statement of the rule the customer faces at settlement |
| Midnite | Commission account 101839 — Midnite Limited; category on the register: remote general betting standard (real events) | In-play events, an acca builder, popular accas and price boosts with maximum-stake limits are visible on the site, alongside the new-customer sports welcome offer; described qualitatively, not as a working promo |
| Star Sports | Commission account 9177 — Star Racing Limited; category on the register: remote general betting standard (real events) | Pre-event and in-play markets with Bet Boosts, Daily Specials and Weekend Enhanced Boosts; in-play coverage spans football, horse racing, golf and US sports |
| Fafabet | Commission account 57385 — Taichi Tech Limited; category on the register: remote general betting standard (real events) | Best Odds Guaranteed on UK and Irish horse racing win and each-way bets from 9am on race days: bigger starting prices paid at the bigger figure |
| Bet600 | Commission account 44731 — Tyche Tech Limited; category on the register: remote general betting standard (real events) | Best Odds Guaranteed on horse racing; bets paid at the bigger of the starting price and the early or show price taken |
The two pure exchanges on this list — Smarkets and Matchbook — run the matched-book model without a sportsbook book attached, and that clarity about what the platform does shows up in the published commission rates. Betfair is the largest licensed UK-licensed matched-book operation, and the Betfair Sportsbook brand sits behind it for the sportsbook side; the two share a commission account and a corporate parent. The remaining brands on the list are sportsbooks that include some exchange-style functionality, and their commission and fee structure follow the sportsbook model rather than the matched-book one.
The rank, in order
1. Betfair. The greyhound-racing grand prix of British exchange punting, Betfair is the platform the matched-betting industry grew up on and the order book on the Premier League is the deepest in the country. Flutter and Betfair merged in 2001, with Betfair chosen as the primary exchange and flutter.com ceasing operations in January 2002 — a corporate lineage that explains the depth of the order book and the range of markets offered. The sportsbook arm publishes in-play, Bet Builder, free live streaming of UK and Irish horse racing and football inside the app and a 90 Minute Payout market. Commission is on a per-account basis and disclosed on the user’s account page; the brand does not publish a single headline rate for all customers, and sharper accounts sit at lower rates than casual accounts. The punter looking for a one-stop shop with both an exchange and a sportsbook falls into Betfair by default.
2. Smarkets. Smarkets’ published standard commission of 2% on net winnings per market is the headline number on the platform’s App Store page — a level that has made the brand the second-largest licensed UK exchange by handle. New customers have been offered 0% commission for 60 days subject to a £10 minimum first deposit, which is a more pointed opening offer than a free-bet token because the value lies in the running-cost reduction rather than the headline stake boost. The order book is shallower than Betfair’s at the busiest moments but the price is rarely worse, and the punter who plans to back a small number of selections a week will not see the difference in liquidity.
3. Matchbook. Matchbook has built its brand on the sharper end of the customer base. The published rate is in the same neighbourhood as Smarkets’ and Betfair’s at the casual end, with a deeper schedule for active customers. The platform offers Bet Builder, multiples, in-play and live streaming of horse racing and greyhounds alongside the exchange order book — a feature set that covers both the casual punter and the matched bettor. The brand’s marketing has, over the years, emphasised low commission and high liquidity at major football events, and that emphasis tracks with the published feature set.
4. Kalooki Sportsbook. A smaller platform run by Kalooki Sports Book Ltd under Commission account 57730, with the operator’s identity stated on its own homepage. The platform publishes itself as a sportsbook rather than an exchange; its place on this list is owed to the licence it holds rather than the depth of its order book. The punter looking at a quieter brand with a clean licence should expect thinner liquidity on niche markets and a friendlier welcome on customer service; a sportsbook rather than an exchange, and the commission model is the sportsbook margin rather than the matched-book commission.
5. BetTom. BetTom’s App Store listing describes a sports welcome offer of 50% back as a free bet up to £50, alongside a matching 50% back up to £50 as free slot funds for casino play, with full terms applying. Read qualitatively: a small-platform welcome broken into a sportsbook arm and a casino arm. The Commission account is 64959, and the regulatory standing is the same as every other licensed UK brand; the punter choosing BetTom is choosing a smaller operation than the top three and accepting the trade-off that comes with it.
6. DAZN Bet. Cash Out is offered but availability is not guaranteed and bets stand if it is unavailable — a plain statement of the rule on DAZN Bet’s help pages. The publishing of that rule is more useful than the rule itself, because it warns the punter that the cash-out button is a feature the punter cannot rely on at every moment of an event. The platform sits in the sportsbook column on this list, not as a pure exchange, and its Commission account is 48756 under DZBT Limited.
7. Midnite. Midnite’s sports betting home page cites Gambling Commission licence 101839 and shows in-play events, an acca builder, popular accas and price boosts with maximum-stake limits. The platform’s sports welcome offer — bet £5 or more on pre-match odds of EVS (2.0) or greater within 14 days of sign-up, receive £25 in free bets and 50 free spins, valid for 7 days — is read qualitatively rather than as a working promo, the terms govern the offer. A punter planning to back shorter-priced selections will fit the minimum-odds criterion comfortably; a punter on longshots will need to read the qualifying-bet terms carefully before claiming.
8. Star Sports. Pre-event and in-play markets with Bet Boosts, Daily Specials and Weekend Enhanced Boosts, plus in-play coverage on football, horse racing, golf and US sports. Star Sports has run its brand around racing, with a sportsbook extension into the major US sports; the platform sits firmly in the sportsbook column on this list.
9. Fafabet. Best Odds Guaranteed on UK and Irish horse racing win and each-way bets from 9am on race days: if the starting price is bigger than the original price, the bigger odds are paid. Racing is the brand’s strongest market, and the BOG concession is the standard racing welcome a UK racing punter expects. The brand sits in the sportsbook column, with the racing focus distinguishing it from a football-led sportsbook.
10. Bet600. Best Odds Guaranteed on horse racing: if the starting price is bigger than the early or show price taken, the bet is paid at the starting price. The BOG concession is the headline feature on the App Store listing and is the platform’s stated distinguishing offer. A punter comparing Bet600 and Fafabet on racing looks at the racing-specific terms rather than the headline; both have BOG, and the rest of the platform’s terms decide the difference.
The implicit verdict
The pure exchanges — Betfair, Smarkets and Matchbook — are the platforms where the matched-book model does what the matched-book model is designed to do: a customer sits opposite another customer at a published price, and the platform takes commission on net winnings. The punter looking for that model picks one of those three, and the difference is the depth of the order book, the published commission rate, and the freshness of the user’s account when it comes to welcome offers.
The sportsbooks on the list — BetTom, DAZN Bet, Midnite, Star Sports, Fafabet, Bet600 and Kalooki Sportsbook — run on the margin model and the bonus model the wider UK market runs on. The punter looking for a sportsbook with a horse-racing specialism picks from the bottom of the list; a punter looking for a sportsbook with a casino arm and a smaller welcome picks from the top of that group.
The fundamentals of a betting exchange in the UK
The premise is small. The exchange is a marketplace where customers bet against each other on the outcome of discrete events, and the exchange itself is not a party to the bets. Bookmakers earn revenue from less favourable odds, while exchanges earn it from commission; exchange odds are usually better because the overrounds are smaller. That single sentence is what the rest of the platform — the order book, the back-or-lay columns, the commission rates — does.
A back bet wagers that an outcome will occur and a lay bet wagers that it will not. The layer takes the role a bookmaker normally plays, and liability is the most a person can lose in the worst case. The most confusion at an exchange is around liability: a £10 back bet at decimal odds 6.00 can win £50 (the backer wins £50 profit on top of the £10 stake, total return £60), but a £10 lay bet at 6.00 has the punter keeping the £10 stake if the selection loses and paying out £50 if it wins. The punter’s stake is £10 and the worst-case liability is £50; that distinction governs position sizing, bankroll management and the math behind every trading strategy on the platform.
Most betting exchanges charge commission as a percentage of a customer’s net winnings per market, and losing bets generally incur no commission. That is the line every exchange draws — winning bets carry the cost, losing bets do not — and the line is where every comparison of commission rates should start. A 2% commission rate is the same number for a £100 winner and a £1,000 winner; the absolute cost is small on a small winner and small on a big winner relative to the total winnings. The punter’s bill is the commission multiplied by the net winnings, and the only way to be sure of the figure is to read the platform’s published rate on the markets they intend to bet on.
Exchanges generally limit odds to between 1.01 and 1000, and bet sizes are not restricted as long as opposing customers match the stake. The cap on odds is a platform rule, not a market rule; the cap on bet size is the counterparty, not the platform. A £50,000 back bet is welcome on a Premier League match if a counterparty is willing to take the other side; without one, the bet sits unmatched.
A few facts anchor the licensed UK field. The minimum age for gambling on a betting platform licensed in Great Britain is 18, and the platform’s verification checks confirm name, address and date of birth before the customer is allowed to deposit or place a bet — even with a free bet or a bonus. The whole licensed market takes part in GAMSTOP, the multi-operator self-exclusion scheme. From 7 May 2019 the verification rule has been in force, and from 31 March 2020 GAMSTOP has been a mandatory licence condition. Those two rules are the floor: every operator on this list meets them and the punter should assume they do.
The exchange’s edge over a bookmaker on the same market is the price. Bookmakers build their margin into the odds — a 5% margin on a two-way market at 1.91 / 1.91 returns 95 pence of every pound bet on it — and an exchange’s commission on net winnings is typically much smaller than that margin would be on an equivalent back bet. The punter looking at a single event’s price at a bookmaker and an exchange can move from one to the other; the punter running an exchange-only strategy does not have the choice. Both are valid; both are clearly licensed; the difference is the model.
A worked example: how the margin shows up in a two-way price
A two-way market at decimal odds of 1.90 on each side — fractional 9/10, “ten to nine on” — looks symmetric, but the symmetry is the trap. The implied probability sums to 1 ÷ 1.90 + 1 ÷ 1.90 = 0.5263 + 0.5263 = 1.0526, or 105.26% of the fair price. The overround is 5.26%, and that figure is the market’s margin — the slice of every pound staked the bookmaker keeps on average. The punter recovers £0.9524 of every pound staked on this market, on average, before commission.
Stated as a band, the overround in this example sits in the 5% to 5.5% region for a quoted 1.90 / 1.90 market, assuming both prices are firm and reflecting the same total at the same moment. A punter watching this market will see the overround move with each price tick: as the favourite shortens from 1.90 to 1.80, the underdog drifts from 1.90 to 2.00, and the overround rises. A wider overround means more cost to the punter; a tighter overround means less. The exchange’s commission is added on top, but the commission is on net winnings only — the loser’s stake is the only money that crosses the platform, and that money crosses gross.
The conversion from fractional odds to decimal is a + b ÷ b for fractional a/b, so 5/1 becomes 6.00, evens (1/1) becomes 2.00 and 9/10 (the example above) becomes 1.90. The conversion is exact; the punter reading fractional odds on a UK horse-racing card and decimal odds on a football match can move between the two without doing the arithmetic each time.
The licensing and regulation of an exchange in the UK
A UK betting exchange runs under a Gambling Commission licence. The framework is the Gambling Act 2005 for Great Britain — England, Scotland and Wales — and the Gambling Commission is the regulator. Since the Gambling (Licensing and Advertising) Act 2014, an operator whose remote facilities are used in Great Britain needs a Commission licence wherever it is based; section 33 of the 2005 Act, as amended, sets out the offence of providing gambling facilities without the licence the Act requires, and section 36 makes clear the territorial scope. A Curaçao, Maltese or Gibraltar licence is not a substitute. Northern Ireland sits outside the 2005 Act and is regulated under older law, so a “GB-licensed” operator is licensed for England, Scotland and Wales but not, in the strict sense, for Northern Ireland.
The Commission registers operators by licence category. The category for a betting exchange is remote betting intermediary; for a sportsbook it is remote general betting standard (real events); for a virtual-event bookmaker it is a separate category; for pool betting it is another; and so on. The categories reflect what the operator does, not the corporate brand name. The public register can be searched by business name, trading name, domain or account number, and the search is the test of who holds a licence. Punters checking a brand’s licence find the entry by the company name rather than the trading name; the licence holder for Betfair, for example, is PPB Counterparty Services Limited rather than Betfair itself.
There is no statutory list of permitted bets. An exchange or sportsbook holds its category licence and offers markets under its own rules and the LCCP — the Licence Conditions and Codes of Practice the Commission publishes and updates. The categories are the legal frame; the markets are the operator’s choice. In-play markets are allowed and are widely offered; esports are treated like other events; virtual events are a separate licence category; politics, TV and novelty markets are offered by some operators and not by others; spread betting is a different product regulated by the FCA.
Financial spread betting is regulated by the FCA, not the Commission. Spreadex, for instance, is FCA-regulated for spread betting and Commission-regulated for fixed-odds betting, and the spread-betting side carries losses that can exceed the deposit because the product is leveraged. The Commission and the FCA are separate regulators, and the punter comparing an exchange to a spread-betting firm should read the licence category before assuming the products are similar.
The customer-protection duties that sit on a GB-licensed operator are detailed and enforced. Identity verification runs before the first deposit. GAMSTOP enrolment is mandatory. The LCCP financial vulnerability check applies when a customer’s deposits minus withdrawals exceed £150 in a rolling 30 days (since 28 February 2025): it is a public-record check (bankruptcy, county court judgments), not an income check. A separate, larger financial-risk-assessment regime has been announced with no start date yet, in a staged plan; the right framing is “announced, staged, no start date”, not “in force”. Deposit limits under RTS 12 are the customer’s choice rather than a state-set ceiling; the operator must offer a gross deposit limit on a fixed time frame.
The credit-card ban in force since 14 April 2020 covers credit cards at the till and credit-card-funded payments through an e-wallet; debit cards and bank-based payments are not covered. A punter looking for an alternative to a debit card at a licensed exchange will find bank transfer, e-wallets and a few operator-specific options; a punter looking for a cryptocurrency deposit will find no GB-licensed operator offers one in steady state, and a punter using a crypto deposit will be at an unlicensed brand.
The promotion rules in force since 19 January 2026 cap wagering requirements on bonuses at 10x and ban mixed-product promotions. These rules apply to GB-licensed operators; an unlicensed brand outside the 10x cap has no such restriction.
The player pays no tax on betting winnings in Great Britain; this is general information rather than tax advice. General Betting Duty is the operator’s tax on gross profits, currently 15%, and from 1 April 2027 a new remote betting rate of 25% applies within General Betting Duty while remote bets on UK horse racing, self-service betting-terminal bets, pool betting and in-person betting remain at 15%. Until 1 April 2027 the remote rate stays at 15%; whether the operator passes duty on through odds is not established. Spread betting has its own rates: 3% financial, 10% other.
The Commission’s public register is the test. Punters checking a brand’s licence will find the entry by company name, account number or domain. The licence number printed on a brand’s homepage is not by itself proof; the proof is the matching entry on the Commission’s register. A licensed brand published on the register is one a punter can stake real money with; a brand not on the register is one a punter cannot.
What an offshore brand costs the punter
A GB-licensed operator carries the checks, limits and protections detailed above. An offshore brand carries none of them. The punter betting at an offshore exchange gives up GAMSTOP coverage, the Commission complaints route, the approved dispute-resolution body, the British consumer redress route for withheld funds, the 10x bonus cap, and the £150 vulnerability check. The Commission’s enforcement is mostly aimed at the operator: cease-and-desist notices, search-engine referrals, work with registrars, hosts and payment providers. The Commission has been given, or is about to receive, court-order DNS blocking powers, and ISP blocking has not been confirmed in operation. The customer-side loss is the protection gap.
There is no offence aimed at a customer who bets at an unlicensed site, on the statutes reviewed for this article. Stating the cost of going offshore is honest; stating the legality is broader than the framework supports. The right framing is what the punter gives up rather than what they do — that framing matches the reality of consumer harm, where a payout dispute at an offshore brand ends in an unresponsive support inbox rather than a British dispute-resolution service.
Safer gambling at a UK betting exchange
GAMSTOP is the multi-operator self-exclusion scheme, mandatory for every online gambling licence since 31 March 2020. Periods are six months, one year, five years, or five years with auto-renewal. After the minimum period ends the exclusion stays in place for a further seven years unless the customer asks GAMSTOP to remove it. GAMSTOP covers online sites and apps; betting shops use a separate service. The punter who has self-excluded through GAMSTOP cannot open a new account at any licensed GB operator during the period; the punter who has not self-excluded but feels the urge can use GAMSTOP’s website directly.
The LCCP financial vulnerability check applies when deposits minus withdrawals exceed £150 in a rolling 30 days. The check is a public-record check — bankruptcy and county-court-judgment lookups — and is not an income check. The punter triggering the check provides the documents the operator asks for and is judged on the public record; the punter looking for an income-based affordability check should know that a broader affordability-check regime has been announced with a staged start date yet to be set.
Deposit limits are the customer’s choice at a GB-licensed operator, and the operator must offer a gross deposit limit on a fixed time frame. The punter who wants to limit their weekly deposit sets it through the operator’s responsible-gambling page; the operator enforces it. Limits set at sign-up are easier to tighten than to loosen after a few weeks, and a punter setting a deposit limit at the top of the wagering range is setting themselves a higher limit than a punter at the bottom.
The Commission requires the operator to interact with customers whose play shows signs of harm. The interactions are the operator’s responsibility: a soft nudge after a losing streak, a check-in after a long session, a request for source-of-funds documents on a bigger withdrawal. A punter who feels their play is sliding should use the operator’s safer-gambling tools; a punter who feels their play has already slipped should self-exclude via GAMSTOP.
Help is available outside the operator. GamCare runs the National Gambling Helpline. GambleAware publishes information and funds treatment. The NHS runs gambling clinics in person and online. Gamblers Anonymous runs peer-support meetings. The punter who has decided that the gambling has to stop has more than one route, and the routes are free.
Cryptocurrency and anonymity at a UK betting exchange
A GB-licensed betting exchange does not offer cryptocurrency deposits and does not allow anonymous play. The verification-before-deposit rule (in force since 7 May 2019) means the punter’s name, address and date of birth are confirmed before the first deposit or bet, including a free bet or bonus; the result is no anonymous play at a licensed site. A punter wanting to bet with bitcoin or another crypto will be at an unlicensed brand, and the protection gap is the same gap an unlicensed fiat punter faces: no GAMSTOP, no Commission complaints route, no British dispute resolution, no operator-side limit enforcement, no 10x bonus cap.
The ledger point is a different one. A cryptocurrency ledger is a public record of transactions; a punter’s identity on the ledger is pseudonymous, not anonymous, and the address history is traceable. A punter thinking a crypto deposit makes them invisible should know that the address history is permanent and that on-chain analytics has been used to identify exchange users in published enforcement actions. Pseudonymity is the right word; anonymity is the wrong one.
A crypto exchange for sports betting is, in practice, an offshore exchange that accepts crypto deposits. The platform’s KYC, AML and gaming rules are those of its own jurisdiction and not the Commission’s; the platform’s marketing language is that of the offshore market. The punter moving from a GB-licensed exchange to a crypto one is moving to a different product with a different cost structure, and the protection gap is the cost they are paying for the move.
How a back bet actually pays: the maths
A back bet at decimal odds of 4.00 for a £10 stake returns £40 if the selection wins. The £40 is the £10 stake plus £30 profit — the punter pays back the stake on top. The formula is return = stake × odds and net profit = stake × (odds − 1). At 1.50 the same £10 stake returns £15 (£10 stake plus £5 profit); at 6.00 it returns £60 (£10 stake plus £50 profit). A combination bet — an accumulator or a multiple — multiplies the odds of the legs together: a treble at 2.00, 3.00 and 4.00 has a price of 24.00, and a £10 treble at that price returns £240 if all three selections win.
The exchange punter sees the same maths from the lay side. A £10 lay at 4.00 keeps the £10 stake if the selection loses and pays out £30 if it wins; the punter’s worst case is the £30 liability. A lay accumulator is constructed as a series of lay bets on the individual legs and combined at the order-book level; the maths at settlement is the same combination logic.
A market’s margin is what the punter pays the platform in expectation. For a two-way market with decimal odds o₁ and o₂ on each outcome, the payout share is 1 ÷ (1/o₁ + 1/o₂), and the margin is 1 minus the payout share. A market at 1.90 / 1.90 has a payout share of 1 ÷ (1/1.90 + 1/1.90) = 1 ÷ 1.0526 = 0.9499, or 94.99%, and a margin of 5.01%. That figure is the platform’s edge across the whole market; a punter betting on either side pays it in expectation.
Operator-by-operator verdicts
What follows is a short judgement on each operator under the criterion the brand is best understood against — for the matched-book purist, for the sportsbook-heavy sports-punter, for the racing specialist. The verdicts are written for the punter reading the comparison table and wondering what each platform actually does for them.
Betfair
The order-book depth at Premier League fixtures and on racing at the major meetings is what no other platform matches at the same scale. The matched-betting industry runs on Betfair’s liquidity, and a matched bettor with a £100 per-leg staking plan will clear most of their free bets on this platform. The corporate history — Flutter and Betfair merged in 2001, with Betfair chosen as the primary exchange — explains why the order book is so much larger than the next competitor’s. The platform’s commission is on a per-account basis and sharper accounts sit at lower rates than casual accounts, and the punter planning a long-run staking plan should ask about the rate their account sits on. The sportsbook arm sits behind the exchange and shares the Commission’s licence account. The punt is settled on the platform’s results service, and Rule 4, non-runner and dead-heat rules apply.
Smarkets
Smarkets’ published standard commission of 2% on net winnings is the headline number to compare against. The platform runs shallower than Betfair at the busiest moments but the price is rarely worse, and a small-staking punter does not see the difference in liquidity. The 0% commission window for 60 days for new customers is a meaningful opening offer, and the punter who plans a moderate staking plan over two months can extract real value from it. The platform is a matched-betting favourite for accounts that have hit a Betfair restriction, and the order book holds up at most fixtures the punter will bet on.
Matchbook
A platform the sharper end of the customer base favours. The published commission rate is in the same neighbourhood as Betfair’s and Smarkets’, with a sharper schedule for active customers. The exchange and the sportsbook sit on the same licence, and the Bet Builder, multiples, in-play and live streaming of horse racing and greyhounds give the punter a feature set that covers matched betting, in-play punting and racing-market trading. A punter with a moderate bankroll and a willingness to manage an order book will find the platform a close third to Betfair and Smarkets.
Kalooki Sportsbook
A smaller sportsbook platform with a clean Commission account, GAMSTOP membership and verification-before-deposit. The punter looking at this platform is not looking for an order book — it is a sportsbook, not an exchange — and the brand’s distinguishing feature is its smaller, friendlier approach to customer service. The liquidity on niche markets is thinner than the platforms at the top of the list, and a racing specialist will not be picking Kalooki over Fafabet or Bet600.
BetTom
A small-platform sportsbook with a welcome offer of 50% back as a free bet up to £50 alongside a matching casino offer. The licence is clean and the platform is GAMSTOP-compliant; the welcome offer is the brand’s distinguishing hook, and a punter reading the offer qualitatively will fit the trigger conditions and weigh the staking plan accordingly. The brand is too small to expect the depth of markets the top sportsbooks offer, but a punter looking for a sportsbook-only experience may find that a feature rather than a bug.
DAZN Bet
A sportsbook whose distinguishing feature is the clarity of its cash-out rule: cash out availability is not guaranteed and bets stand if it is unavailable. The wording is unusual in the field because most operators leave the rule implicit; DAZN Bet publishes it on its help pages and the punter reading the page is forewarned. A punter planning a heavy in-play staking plan needs that clarity, and the platform’s value is in the explicit terms rather than the explicit feature set.
Midnite
Midnite’s strength is the visibility of its product page — in-play events, an acca builder, popular accas and price boosts with maximum-stake limits are all on the home page, and a punter reading the page sees the platform’s full product without searching for it. The sports welcome offer is read qualitatively rather than as a working promo. The platform sits between DAZN Bet and Star Sports in size, and the customer who likes a cleaner product page than the legacy sportsbooks offers will find Midnite easy to live with.
Star Sports
A racing-led sportsbook with US-sports and football coverage on top. The daily specials and weekend enhanced boosts are the brand’s distinguishing feature, and a punter reading the terms will see the maximum-stake limits printed alongside. The platform is a sportsbook, not an exchange, and an exchange customer looking at this list will not pick Star Sports for the order book.
Fafabet
A racing-led sportsbook with Best Odds Guaranteed on UK and Irish racing win and each-way bets from 9am on race days. The BOG concession is the standard racing welcome a UK racing punter expects, and the platform is built around it. The punter picking Fafabet is picking a racing-specialist sportsbook, and the BOG terms should be read carefully on the morning of a major meeting.
Bet600
A racing-led sportsbook with Best Odds Guaranteed on horse racing — bets paid at the bigger of the starting price and the early or show price taken. BOG is the headline offer and the brand’s distinguishing feature, but the racing-only focus limits the punter looking for a depth of football or US sports. The punter picking Bet600 is picking a racing-only sportsbook.
Calculator: what an exchange’s margin costs the punter
A two-way market at decimal odds of 1.90 / 1.90 — fractional 9/10 — is the example used here. The implied probability of each side is 1 ÷ 1.90 = 0.5263, and the sum across the two outcomes is 1.0526, or 105.26% of the fair price. The overround is therefore 5.26%, and the platform’s margin on this market is 5.26%: the platform keeps 5.26p of every pound staked on this market, on average.
Stated as a band, the market’s margin sits in the 5% to 5.5% region — the implied probability sums to between 1.0500 and 1.0550, which is the standard range for a tightly priced two-way market on a Premier League match. A punter watching the order book will see the figure move with every price tick: as the favourite shortens, the underdog drifts, and the overround rises. The exchange punter’s net cost on a winning bet is the commission on net winnings, added to the overround already absorbed by the wider market; the exchange punter’s net cost on a losing bet is the overround only, because commission is on winning bets.
The exchange’s edge over the bookmaker on the same fixture is in the overround. A bookmaker offering the same fixture at 1.85 / 1.85 would have an overround of 8.11% (1 ÷ 1.85 × 2 − 1 = 8.11%), and the punter paying 1.85 each way is paying almost 3 percentage points more in margin than the punter paying 1.90 each way at the exchange. Commission then sits on top of the lower overround, and the punter’s running-cost equation reads: bet small amounts of stake at tight overround plus commission on net winnings. The math points the punter to the exchange on big favourites, where the lower overround compounds over many bets.
A three-way market at decimal odds of 3.00 / 3.40 / 2.10 (home / draw / away, fractional 2/1, 5/2 and 11/10) has implied probabilities summing to 1 ÷ 3.00 + 1 ÷ 3.40 + 1 ÷ 2.10 = 0.3333 + 0.2941 + 0.4762 = 1.1037, and the overround is 10.37%. The football punter pays about double the margin a two-way tennis punter pays, which is why football markets at a sportsbook are typically wider overround than two-outcome sports. The exchange punter reading these three prices will work out the same figure and decide whether the price is worth a stake.
Frequently asked questions
How does a betting exchange work?
A betting exchange is a marketplace where customers bet against each other on the outcome of discrete events, with the operator taking a slice of net winnings as commission rather than baking a margin into the odds. A back bet wagers that an outcome will occur; a lay bet wagers that it will not, with liability the most a person can lose in the worst case. The exchange shows a back price and a lay price on the same selection, and the bet is matched when a counterparty takes the other side at the same price.
What is the difference between an exchange and a bookmaker?
A bookmaker sets the prices and takes the other side of each bet, earning revenue from the margin baked into the price. An exchange shows a marketplace of prices set by customers, with the platform earning revenue from commission on net winnings. Exchange odds are typically better than bookmaker odds on the same selection because the overround at an exchange is smaller. The bookmaker has a stake in which side wins; the exchange has no stake in any bet and earns the same commission regardless of outcome.
How can a punter check that a brand holds a Gambling Commission licence?
Search the Gambling Commission’s public register by business name, trading name, account number or domain; the entry’s licence categories confirm what the company is licensed to do. The licence number on a brand’s homepage matches the entry on the register; the match is the test. A brand not on the register is not licensed for customers in Great Britain regardless of what its homepage says.
How is the return on a back bet worked out from the stake and the odds?
The return is stake × decimal odds; the net profit is stake × (decimal odds − 1). A £10 back bet at decimal odds of 4.00 returns £40 if the selection wins — the £10 stake plus £30 profit. A combination bet has the odds of the legs multiplied together: a treble at 2.00, 3.00 and 4.00 has a price of 24.00, and a £10 treble returns £240 if all three legs win.
What is a betting market’s margin and how does it show up in the odds?
A two-way market at decimal odds o₁ and o₂ on each outcome has a payout share of 1 ÷ (1/o₁ + 1/o₂) and a margin of 1 minus the payout share. A market at 1.90 / 1.90 has a payout share of 94.99% and a margin of 5.01%; a market at 1.85 / 1.85 has a payout share of 91.89% and a margin of 8.11%. A wider overround means more cost to the punter; the exchange punter pays the overround on every bet and commission on net winnings.
Betting sites & exchanges – Cricket betting
Content created by the «Cricket betting» team
